Support CleanTechnica’s work through a Substack subscription, on Patreon, or on Stripe. Help us produce all the original, high-quality content we publish week after week despite the challenges of AI deleting content, anti-social media, inflation and other obstacles.
I haven’t covered a Tesla earnings release or call in a while, but I thought I’d give a quick recap since this quarter was pretty interesting. Last quarter I wrote this after the delivery release, but I didn’t write the earnings call.
Observations from the shareholder platform:
- Gross margin has increased greatly, from 16.8% last quarter to 19.6%
- Operating margin almost doubled, from 1.4% to 2.6%
- Regulatory credits fell from $146 million last quarter to $116 million, well below $417 million a year ago or a high of $542 million in the fourth quarter of 2025.
- Tesla announced that it has the largest order book ever for both passenger vehicles and energy storage.
- Model Y capacity in Austin increased from >250,000 to >375,000 (annual)
- The semi capacity went from commissioning to 25,000 (annual)
- California Optimus production moved from construction to initial ramp
- Cortex training estimate increased a bit, from >205 MW to >225 MW, but the plan is to expand to 400 MW by the end of the year (that’s not a change)
- No change in battery cell manufacturing capacity
- The capacity of the Texas Megapack went from being in service to 50 GWh (a little more than the 40 GWh of California and Shanghai)
- FSD fixation rate on new vehicles in North America increased to 75%; Active subscriptions up to 1.74 million from 1.48 million last quarter.
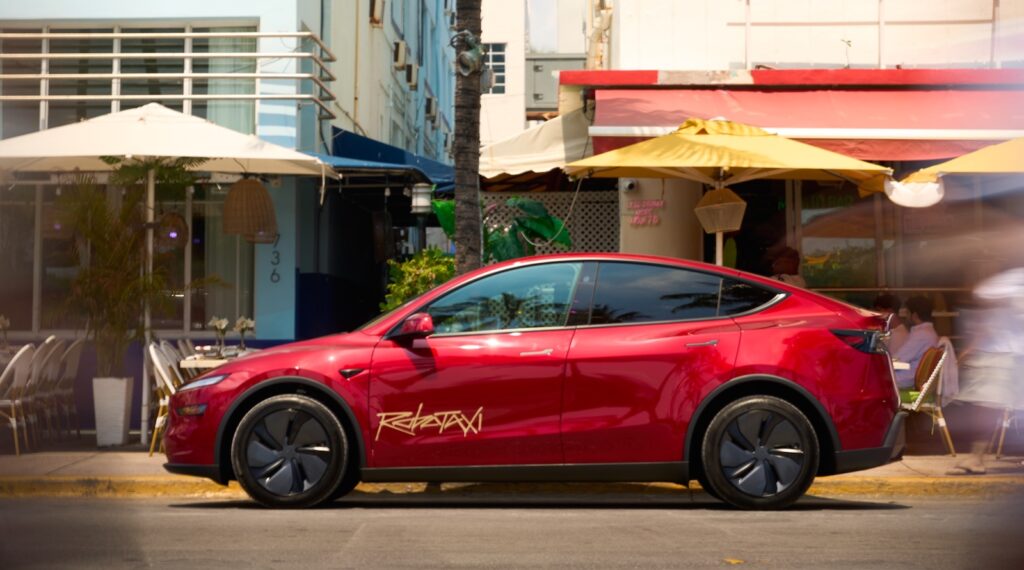
- Unattended Robotaxi miles increased dramatically from last quarter (looking at the chart): up to approximately 1.7 million from 250,000. They also announced today that it’s up to 3.3 million miles!
- Published a new site to track a lot of information we have wanted for years!
Other highlights (AI generated):
- Revenue practically stable at $28.05 billion (in line with consensus). Automotive revenue declines ~3% YoY; Energy generation and storage revenue fell ~16% to ~$2.9 billion (customer rebates partly related to tariffs); Services and Others rose sharply to ~$4.6 billion.
- GAAP Net Income $787 million (down 43% year-on-year); Non-GAAP Net Income ~$1.7B / $0.48 EPS (beats consensus). Includes changes in the market value of Bitcoin and SpaceX holdings.
- Surprising positive free cash flow of $1.53 billion (against expectations of a multimillion-dollar burn). Capital spending totaled $4.73 billion, well below the $7 billion to $8 billion that many expected.
- Full-year capex forecast reduced to ~$20 billion (up from $25 billion previously). Management said they are managing capital deployment more efficiently and plan to fund most of it with operating cash flow.
- Battery availability (not demand) was the limiter on car volumes. Still, they ended the quarter with the largest passenger vehicle order book in four years and the highest energy storage order book/rate ever.
- Record quarterly deliveries in Canada, Australia, Japan and Taiwan; Record production at Gigafactory Berlin.
- Energy storage deployments 13.7 GWh (+10% year-on-year). First Megapacks built entirely with Tesla’s own Nevada LFP cells were sent. The Texas megafactory is already in production (planned 50 GWh).
- Optimus: Production has begun on high-volume lines in Fremont – “the first production-quality robots” suitable for a commercial product.
- Construction of Austin Fab (Terafab) continues; equipment start-up planned for 2027.
Observations of the call
- The production target of 5 million vehicles per year by 2030 is new; Unfortunately, last year the target was a rate of 5 million vehicles per year by the end of 2028.
- Elon expects the Megapack business to expand in volume and margins as data center demand accelerates.
- Tesla hopes to deploy unsupervised FSD on customer-owned vehicles in the second quarter of next year (of course, the target has slipped MANY times).
- Tesla hopes to sell Cybercabs to others before the end of the year.
- Maps Overhaul: Big AI-powered map and navigation improvements coming in the coming months; The system learns the preferences of both the individual user and the fleet.
- Cybercab production is increasing rapidly and the company claims it is easy to manufacture thanks to 50% fewer parts.
- It appears that cyber taxis will be limited by regulations in the US and around the world.
- For years, the question we all asked was: “Is Tesla waiting to scale without oversight because the software has to improve or for regulators to approve it?” They seem to be happy with the quality of the software, but only in geofenced areas (unlike the long-ago promise that it would not be geofenced). This is annoying for existing owners, but it won’t affect Tesla’s ability to scale to many cities and generate significant revenue.
- One analyst asked whether FSD’s price would be forced to drop as other companies developed competitive software. Tesla executives claimed that FSD is much more difficult to develop than most people think. It’s easy to develop a demo that works 90% of the time, but it’s very difficult to solve all the edge cases.
Other highlights (AI generated):
- Elon: The biggest driver of vehicle demand right now is fully autonomous driving.
- Cybercab’s fleet in Austin has grown approximately 10-fold since its September 3 launch. Next cities are being planned (Dallas is mentioned as an early candidate). Robotaxi’s revenue is expected to be notable in 2027 and more significant later that year.
- Unsupervised FSD for everything-oriented customer-owned vehicles Second quarter of 2027 (Ashok). Cybercab customer availability is closer to 2027, but Elon emphasized that this is primarily transportation as a service rather than a vehicle most people will own.
- Optimus: It is expected to take about a year (maybe a little more) to reach an annualized rate of ~1 million units (20,000/week). The initial clients will be industrial; External customers look more like late 2027. Temper expectations: There is still a lot of reliability, wear and tear, and AI work left.
- Hoping for broader EU FSD approval in the coming months or Q1 (timeline not entirely under Tesla’s control). Four new approvals from EU countries already since the second quarter; They currently live in nine EU countries, with more than 100,000 customers and more than 160 million kilometers registered.
- Obtained ~$30 billion of short-term debt capacity to help fund future capital expenditures if necessary. Capital spending will increase more significantly in 2027 and become “notable in tens of billions” in 2028 (Optimus lines, AI computing, Cybercab, Terafab, etc.).
Conclusion
There is a lot of little good news. Tesla continues to promise vehicle growth, but it produces roughly the same number of cars each quarter. This seemed to be the first call where they are rapidly scaling Robotaxi rather than promising to do so in the future. It seemed to coincide with the launch of Cybercab last month. Since the Model Y has the same computer and cameras, many people (including me) thought they would scale the Model Y Robotaxi service first and then add Cybercabs. It appears that the software improved around the same time Cybercab production began. I guess it’s a happy coincidence.
As for traditional car sales, they clearly have huge demand (which is very different from other battery EV manufacturers in the US), which is due to both FSD and high oil prices caused by the Iran and Ukraine wars. They claim they are ramping up production in Austin and Berlin, but it doesn’t appear to be enough to reduce the backlog. Tesla could sell many more cars if it had some inventory. Many people cannot wait long to purchase a new car, as they usually buy it due to a lease ending, an accident, or a breakdown of an existing car. Those people have to buy a used Tesla (that’s why this page shows CarMax selling a 2026 Model Y with 6,000 miles for $4,000 more than a new 2027 Model!). You can get more details here on the CarMax site.
If you want to take advantage of my Tesla referral link to get three months of fully autonomous driving, here’s the link: But if another owner helped you more, use their link instead of mine.
Disclosure: I am a Tesla shareholder [TSLA] and XPeng [XPEV]. But I am not offering any investment advice of any kind here.
Sign up for CleanTechnica’s Weekly Substack to get in-depth analysis and high-level recaps from Zach and Scott, subscribe to our daily newsletter, and follow us on Google News.
Do you have any tips for CleanTechnica? Do you want to advertise? Want to suggest a guest for our CleanTech Talk podcast? Contact us here.
Subscribe to our daily newsletter to receive 10-15 new cleantech stories per day. Or sign up to receive our weekly newsletter on the week’s top stories if the daily grind gets too much.
CleanTechnica uses affiliate links. See our policy here.
CleanTechnica Comment Policy