Support CleanTechnica’s work through a Substack subscription, on Patreon, or on Stripe. Help us produce all the original, high-quality content we publish week after week despite the challenges of AI deleting content, anti-social media, inflation and other obstacles.
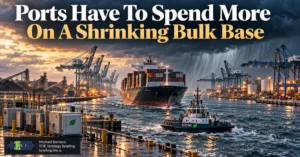
Ports are being asked to make infrastructure decisions that will last thirty, forty or fifty years, while several of the assumptions that funded their existing infrastructure are changing at the same time. Ships are getting bigger, requiring deeper channels, bigger cranes and more capable tugboat fleets. Climate disruption is increasing the cost of keeping ports and their connections to the hinterland reliable. Ports are also having to decarbonize their own operations as regulators and customers put more weight on supply chain emissions. Meanwhile, some of the cargo flows that have historically paid for canals, berths, rail connections, storage areas, port services and shared infrastructure are entering structural decline.
Approximately 40% of current shipping tonnage is coal, oil, petroleum products, liquefied natural gas and liquefied petroleum gas, while raw iron ore contributes approximately another 15%. Electrification directly attacks the first group by reducing the amount of fuel that must be transported, while the increased use of scrap metal, electric arc steelmaking, and changes in iron reduction sites put pressure on the second. The result is an uncomfortable capital problem: ports need to continue spending on resilience and capacity even as some of the cargo volumes and revenues that justified legacy infrastructure weaken.
The TFIE Strategy Briefing’s full analysis looks at the toughest question behind those trends: what happens when many ports respond to the reduction in bulk business with strategies that individually make sense but can’t all succeed at the same time?
Port authorities are not immune to the transition. Major ports are planning for lower fossil fuel volumes, tougher competition for containers, new industrial activity and possible growth in hydrogen, ammonia, methanol, biofuels, circular materials and other transition feedstocks. The problem appears when these strategies are considered together. A bulk port can replace some lost coal traffic by gaining container share from a competitor, and a well-positioned port can win new industrial or energy-related business, but all competing ports cannot simultaneously take market share from each other. The same problem applies to green bulk: there will be new commodity flows, but electrification removes huge amounts of fuel demand rather than replacing each ton of fossil fuel with a ton of another traded molecule.
That collective arithmetic is important because spending needs are moving in the opposite direction. Larger ships place greater demands on berthing infrastructure, channels, cranes and maneuverability, while climate resilience increasingly extends beyond the port itself. A terminal can harden its docks, drainage and electrical systems and still lose performance because flooding cuts rail connections, low river levels reduce barge capacity, drought limits a canal or closes another port in the service rotation. The useful unit of resilience is not only the fenced port area but the transportation network that connects ships, terminals and the hinterland.
In that context, electrification has an unusually broad investment case because its usefulness does not depend largely on which load forecast turns out to be correct. Electric cranes and yard equipment remain useful whether a terminal handles containers, steel products, food, machinery or transitional products. Battery electric tugs can assist ships regardless of what they are carrying. Coastal energy can serve vessel calls while helping to justify larger grid connections, substations and power management systems that can then support trucks, port vessels, inland vessels, batteries and industrial customers. The same electrical infrastructure can serve several different versions of the port’s future rather than relying on a commodity thesis.
That’s not an argument for electrifying all legacy assets. A coal terminal approaching the end of its commercial life should not automatically receive electrical infrastructure sized for another forty years, nor should it automatically receive a climate retrofit intended to protect it until the 2070s. Ports still have to decide which assets are likely to remain useful, which declining cargoes they can continue to pay for, which replacement businesses are truly theirs to win, and which facilities should be converted or retired.
The strongest argument is for durable shared infrastructure: grid connections, substations, container and general cargo handling, road and rail interfaces, tugboats, port vessels, coastal energy and inland vessel connections. Such investments can reduce operating costs and emissions in several plausible freight futures, while reducing the consequences of being wrong about whether ammonia, methanol, hydrogen or some other commodity becomes important at a particular port.
The strategic problem facing ports is broader than the decarbonization of an industry that is supposed to continue growing along familiar lines. Some ports will grow, others will receive cargo from neighbors, some will successfully reinvent themselves, and others will shrink, although they will still need to maintain a capable and resilient infrastructure for the business that remains. An electrification-based strategy doesn’t solve those competitive options, but it is less reliant on guessing the winning load mix decades in advance.
Read the full TFIE Strategy Briefing analysis to learn about cargo projections, climate network evidence, competing port strategies and the port and inland maritime path behind the argument.
Sign up for CleanTechnica’s Weekly Substack to get in-depth analysis and high-level recaps from Zach and Scott, subscribe to our daily newsletter, and follow us on Google News.
Do you have any tips for CleanTechnica? Do you want to advertise? Want to suggest a guest for our CleanTech Talk podcast? Contact us here.
Subscribe to our daily newsletter to receive 10-15 new cleantech stories per day. Or sign up to receive our weekly newsletter on the week’s top stories if the daily grind is too much.
CleanTechnica uses affiliate links. See our policy here.
CleanTechnica Comment Policy