Support CleanTechnica’s work through a Substack subscription, on Patreon, or on Stripe. Help us produce all the original, high-quality content we publish week after week despite the challenges of AI deleting content, anti-social media, inflation and other obstacles.
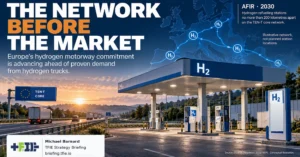
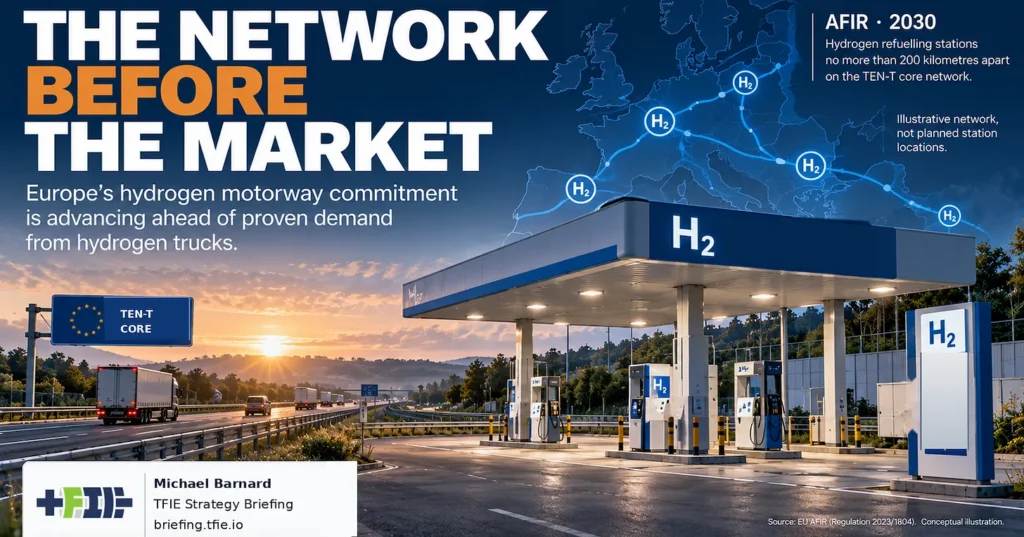
Europe is building a hydrogen refueling network before there is a large hydrogen truck market to support it. Under the Alternative Fuels Infrastructure Regulation, hydrogen stations are supposed to be available along major motorway corridors at intervals of no more than 200 kilometers by 2030, with additional coverage at designated urban nodes. A European assessment estimates that an AFIR-compliant network could require approximately €2.1 billion of capital investment.
The political logic is understandable. Truck operators are unlikely to buy hydrogen vehicles if they cannot reliably refuel them across borders, while station investors are reluctant to build without customers. The problem is that Europe is not the first jurisdiction to try to solve this coordination problem by promoting infrastructure ahead of demand. South Korea has already carried out a much more mature version of the experiment, and its station’s economics should be treated as a warning.
I examine that comparison in Europe’s Hydrogen Highway Bet. The deeper analysis looks at South Korea’s operating subsidies, the strongest breakeven point, the economics of hydrogen supply, and what Europe should demand before committing more AFIR capital.
As of August 2026, South Korea had installed 493 hydrogen refueling units, reaching 74.7% of its target of at least 660 by 2030. Hydrogen vehicle registrations were much further behind, at 49,220, just 16.4% of the government’s target of 300,000 vehicles. Those figures are not utilization rates, but they show that the policy program was much more successful in building infrastructure than in creating the customer base intended to support it.
The financial evidence is more important. Of 258 commercially active stations assessed in the first half of 2026, 208 received government support to cover operating losses, or 80.6%. Several relatively new stations had already ceased operation, with poor business prospects or financial losses among the reasons cited. The subsidy program has eligibility limits, so the remaining stations cannot simply be classified as profitable, but the scale of ongoing support is difficult to reconcile with the idea that the initial infrastructure automatically matures into a commercially self-sustaining network.
South Korea did not neglect the vehicle sector of the market. Hydrogen vehicles received purchase incentives, station construction was subsidized, operating losses were supported, and industrial policy promoted hydrogen production and infrastructure. The country offers serious proof of the theory that the government can solve the chicken and egg problem by supporting supply and demand together. The result is a substantial network whose economy still relies heavily on public support after years of coordinated intervention.
Jeonju Pyeonghwa provides an apparent counterexample worth exploring. The station reported reaching operational break-even in 2024 while serving concentrated demand for hydrogen buses. However, the refueling infrastructure was subsidized, it is unclear whether the break-even point included amortization of capital expenditure, and whether the hydrogen was of fossil origin. That result is important because it shows that hydrogen refueling can somewhat work economically under favorable conditions, but those conditions are very different from a built highway station because the next facility must be within a regulatory space limit. Buses return predictably, use large amounts of fuel, and allow infrastructure to be designed based on known demand.
Europe should make that distinction central to AFIR. A station linked to committed fleets or dense freight activity can be tested with identifiable customers and expected kilograms sold. A geographically mandated station may exist primarily because network coverage requires it, making its utilization dependent on a trucking market that has not materialized and is unlikely to do so.
The cost of fuel adds another layer of risk. The economics of hydrogen refueling in South Korea largely developed around relatively inexpensive hydrogen derived from fossils and petrochemical byproducts. That helps the economics of the stations, but weakens the climate argument. Renewable hydrogen improves life cycle emissions while substantially increasing fuel costs, meaning economics become tougher just as fuel becomes more consistent with policy objective.
Europe faces the same tension. Its hydrogen industry remains overwhelmingly conventional, while renewable hydrogen costs materially more before transport, compression and dispensing are included. Therefore, a hydrogen station can satisfy an infrastructure mandate without demonstrating commercially attractive fuel prices or lifecycle emissions reductions that justify the policy.
The competitive market is also moving. Electric trucks are entering service in increasing numbers, while high-power charging is being deployed. Each truck that goes directly to batteries reduces the addressable demand available to recover the fixed costs of hydrogen stations. A network built today must be evaluated based on the technologies that are likely to compete with it over the life of the assets, not based on the transportation market as viewed when the spacing requirement was drafted.
Europe does not need to close existing useful hydrogen stations or prevent projects with committed fleet demand from proceeding. What you should reconsider is the assumption that geographic coverage should continue to expand automatically. New stations should face explicit tests of expected performance, total capital and operating costs, required public support, price and provenance of hydrogen, and the climate value of the transportation they actually enable.
South Korea’s experience shows the danger of treating infrastructure deployment as proof that a market exists. It built much of its planned network, demand is long delayed, and operational support remains widespread. Europe has the advantage of seeing that outcome before completing its own network, and the AFIR review should use it to distinguish strategically useful stations from potential white elephants that might require public support long after their construction subsidies are forgotten.
The TFIE Strategy Briefing’s full analysis delves into Jeonju’s economy, the history of Korean subsidies, the costs of hydrogen tied to fossils versus renewables, and a phased framework for testing Europe’s minimum grid before expansion.
Sign up for CleanTechnica’s Weekly Substack to get in-depth analysis and high-level recaps from Zach and Scott, subscribe to our daily newsletter, and follow us on Google News.
Do you have any tips for CleanTechnica? Do you want to advertise? Want to suggest a guest for our CleanTech Talk podcast? Contact us here.
Subscribe to our daily newsletter to receive 10-15 new cleantech stories per day. Or sign up to receive our weekly newsletter on the week’s top stories if the daily grind is too much.
CleanTechnica uses affiliate links. See our policy here.
CleanTechnica Comment Policy